General liability
Evaluate protection for covered third-party bodily injury, property damage, and other liability exposures arising from your operations.
Your work, contracts, people, vehicles, and property shape the risk. We build the insurance review around how your business actually operates.
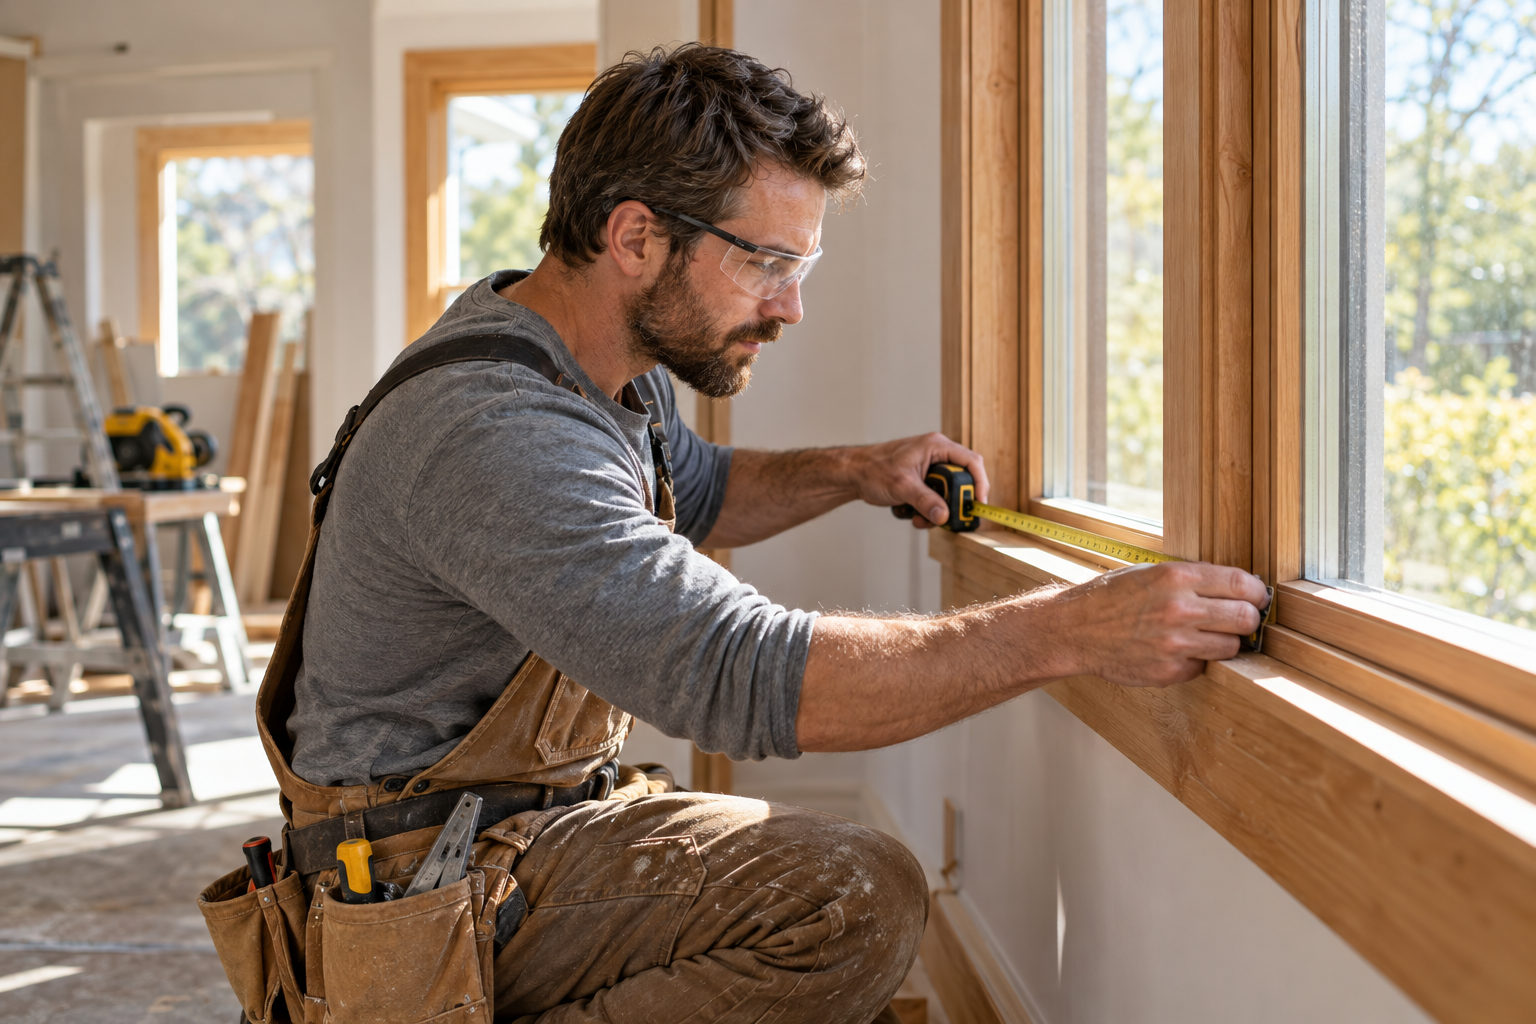
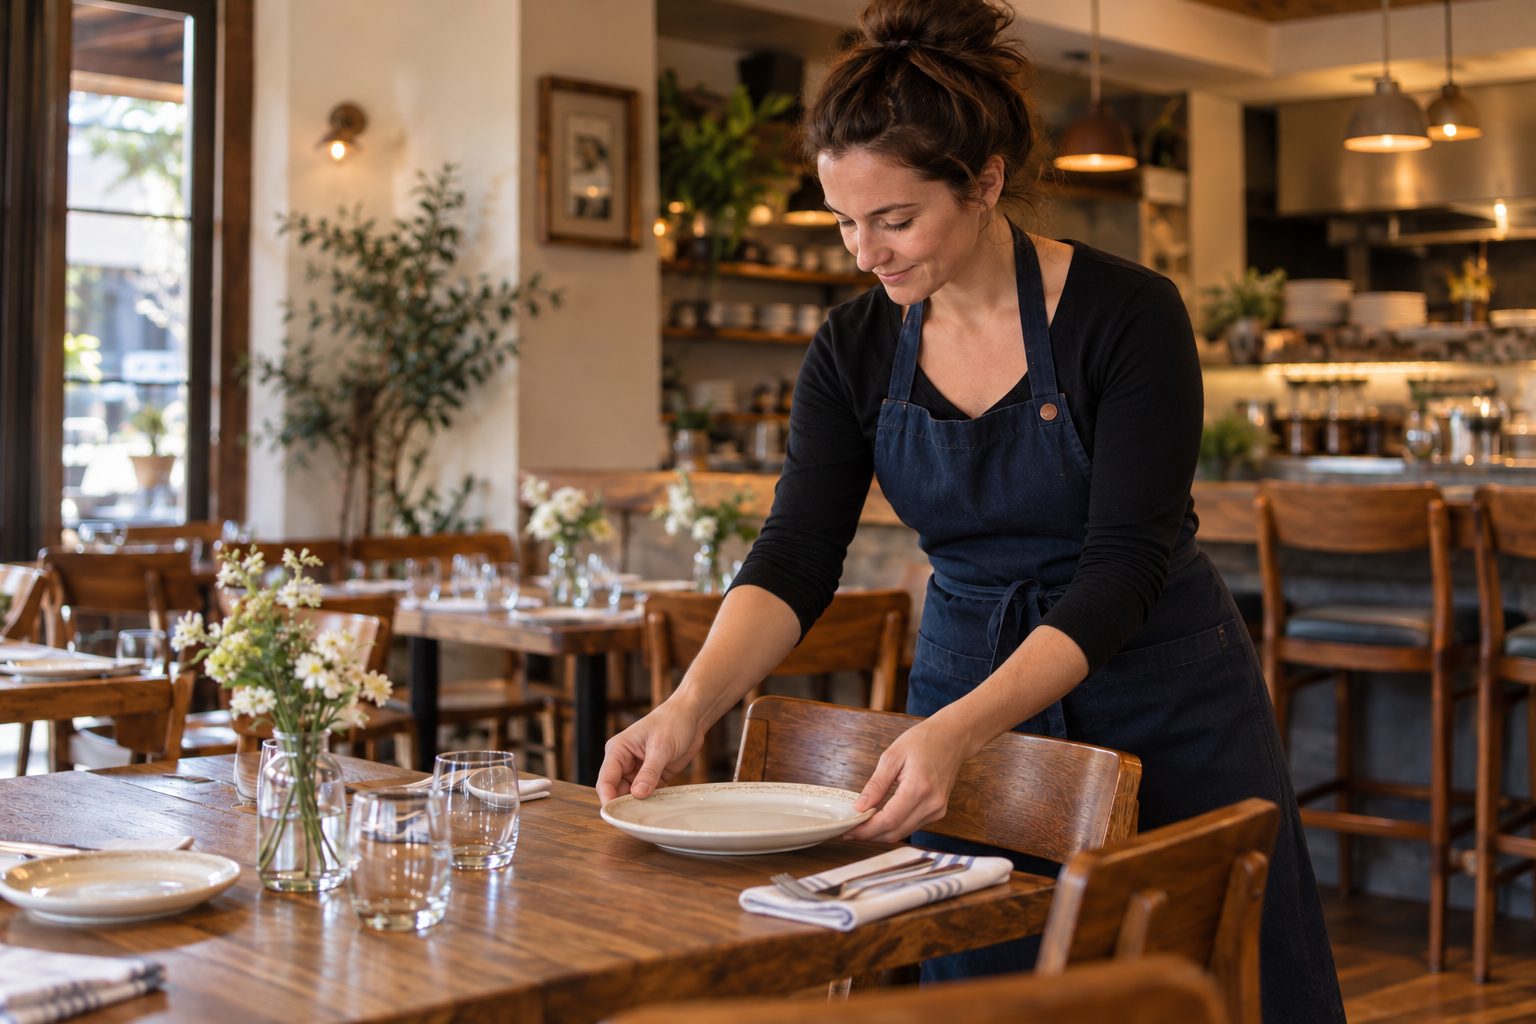
A contractor’s tools and job sites call for a different review than a restaurant’s kitchen, dining room, and staff. We start with your actual operations, then review coverage options and requirements.
Coverage availability depends on business activities, eligibility, and underwriting.
We review the details across your policies so each coverage serves a defined purpose.
Evaluate protection for covered third-party bodily injury, property damage, and other liability exposures arising from your operations.
Consider coverage for eligible work-related employee injuries and illnesses, along with the requirements affecting your business.
Match vehicle use, drivers, operating radius, and ownership to liability and physical damage coverage.
For eligible businesses, review a package combining property and liability with available additional coverages.
Evaluate buildings, equipment, inventory, business personal property, and business income exposures.
Review trade-specific operations, tools and equipment, job-site exposures, subcontracting, and contract requirements.
Texas lets most private employers opt out of workers’ compensation. Some employers and projects have coverage requirements, including certain government contracts.
We also place occupational accident and other nonsubscriber options for eligible businesses. These options differ from statutory workers’ compensation in benefits, protections, and employer obligations.
Source: Texas Department of Insurance workers’ compensation guide.
Our Comprehensive Underwriting Audit includes a courtesy review of coverage, exposure, eligibility, and classification accuracy. It identifies coverage, underwriting, and file-positioning issues before renewal decisions are made.
We organize the context behind your loss history: what happened, what management did, and the outcome, supported by available documentation.
We maintain a dated record of operational changes and corrective measures so the renewal file reflects how your business is managed today.
Start a conversation about your coverage, your equipment, or your next renewal.