Commercial Auto Liability
Review liability protection for covered injuries and property damage arising from the operation of scheduled commercial vehicles.
Operations · Drivers · TerritoryCoverage built around the way you haul. A renewal file that explains your loss history, management response, and operation today.
Equipment, freight, contracts, drivers, and operating territory all matter. We review the coverage structure against those details.
Review liability protection for covered injuries and property damage arising from the operation of scheduled commercial vehicles.
Operations · Drivers · TerritoryMatch cargo coverage to the commodities hauled, contract obligations, handling practices, limits, and exclusions.
Commodities · Contracts · LimitsEvaluate protection for eligible tractors, trucks, and trailers against covered collision and other physical damage exposures.
Schedules · Values · DeductiblesConsider business liability exposures alongside commercial auto coverage, with attention to the operation and applicable policy terms.
Premises · Operations · Policy termsConsider coverage for physical damage to non-owned trailers when a qualifying written interchange agreement applies.
Review eligible liability protection for certain non-business uses of a leased truck. Terms and exclusions require careful review.
Evaluate eligible accident benefits for owner-operators and other qualifying arrangements. This is distinct from workers’ compensation.
Availability, eligibility, limits, and terms depend on the operation and underwriting. Coverage is determined by the issued policy.
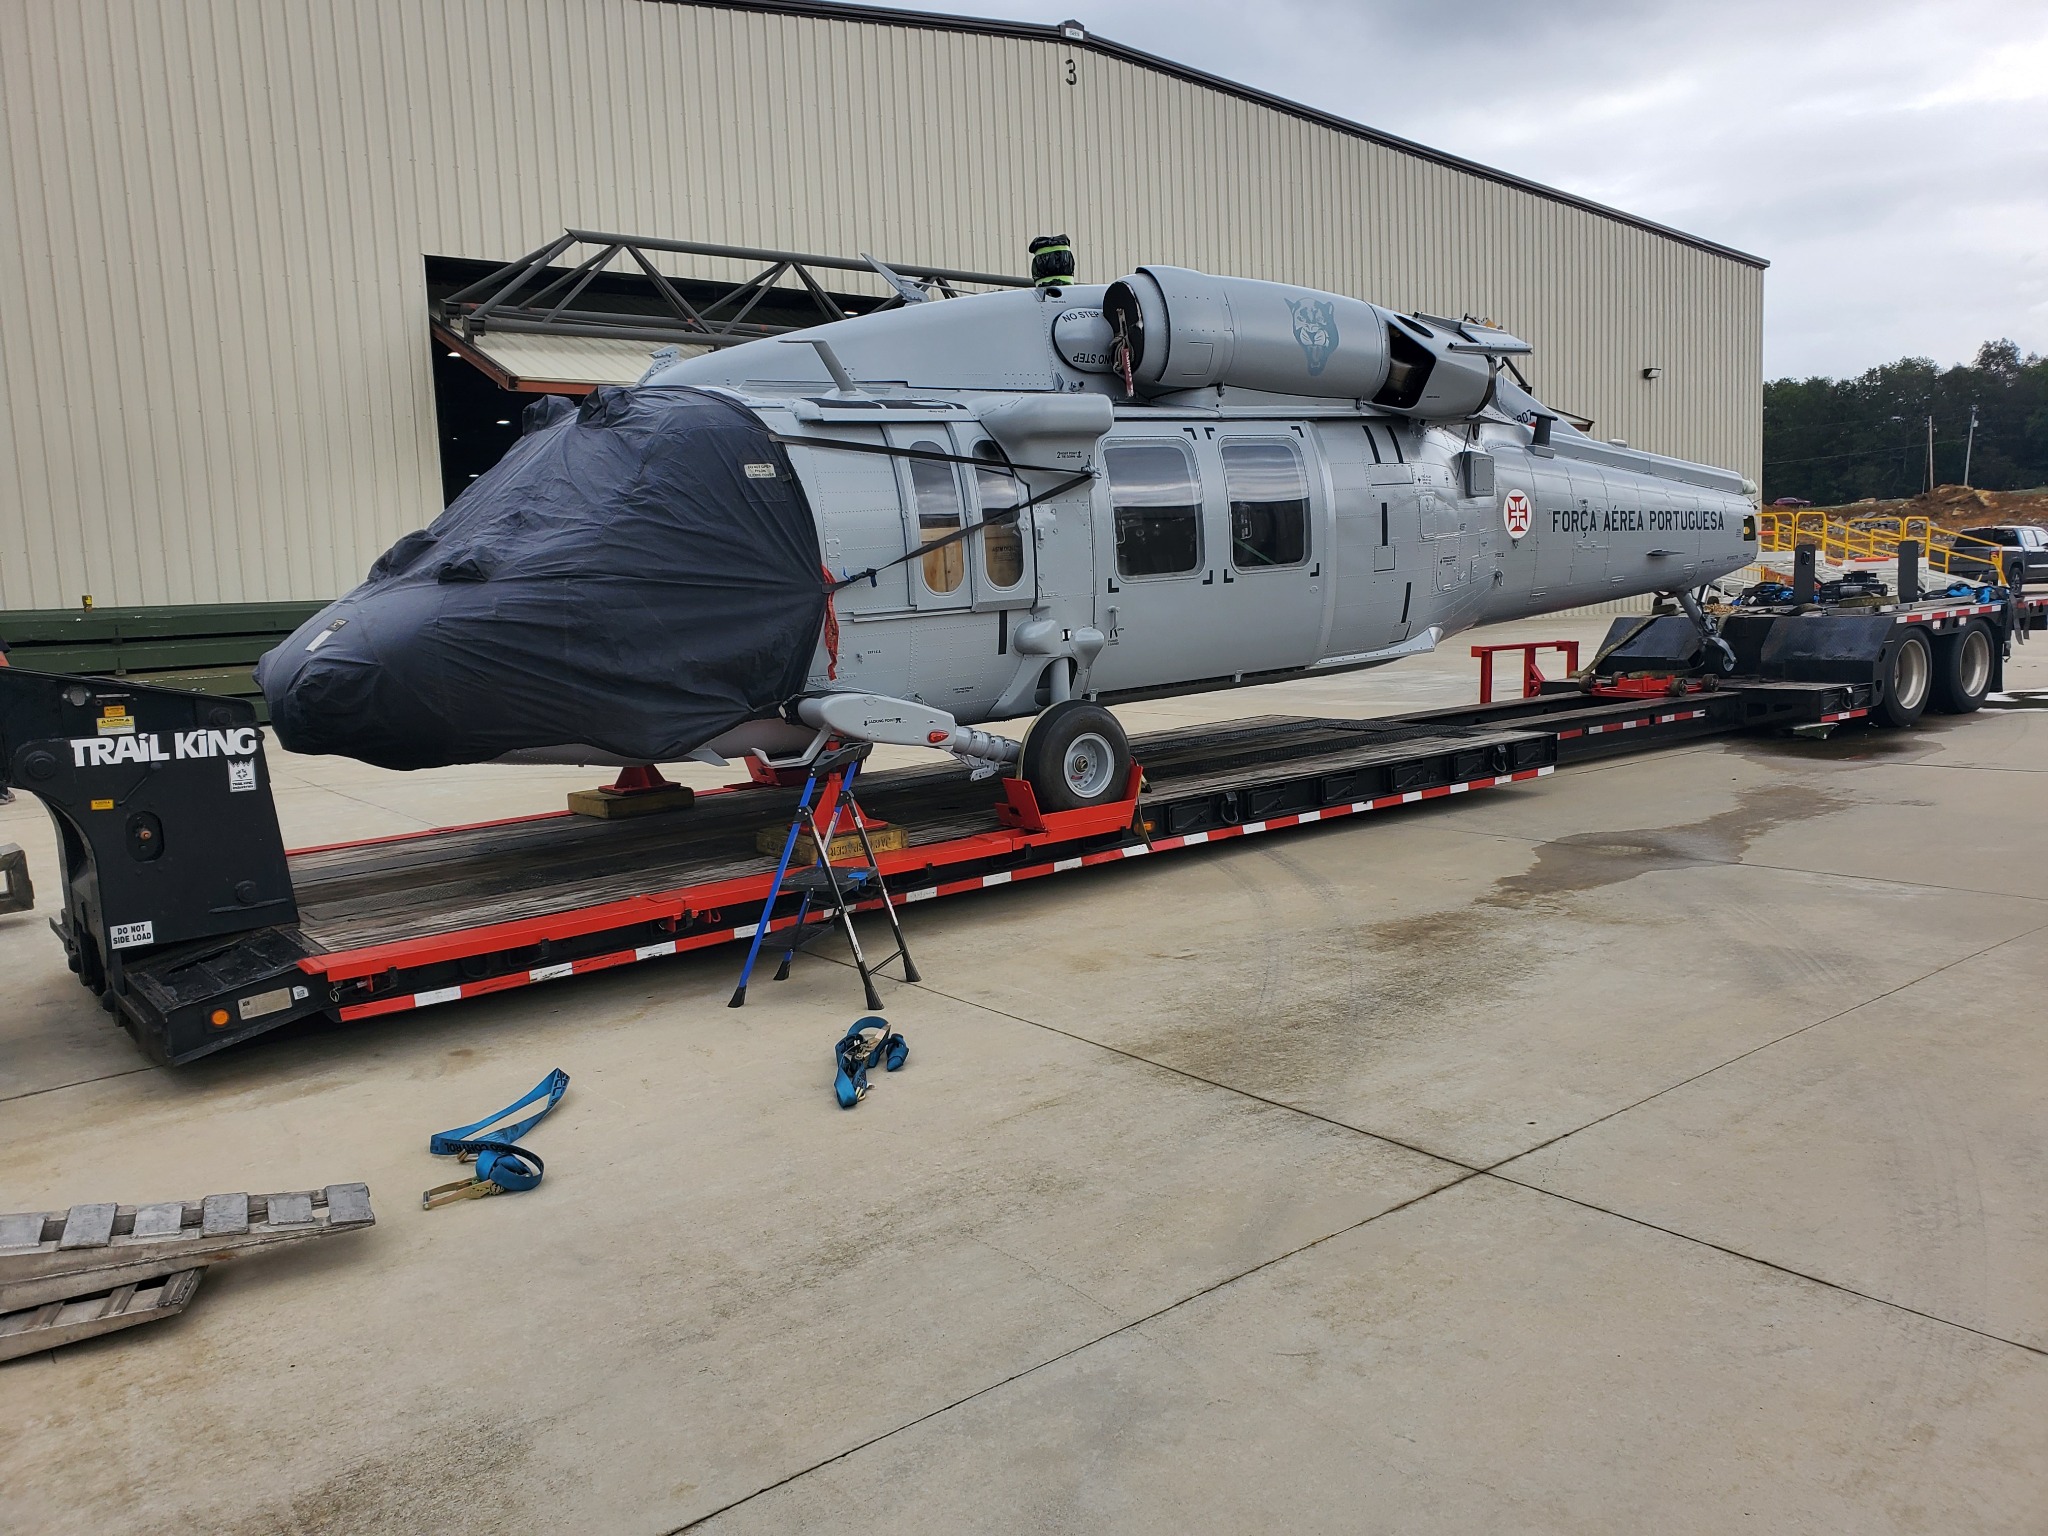
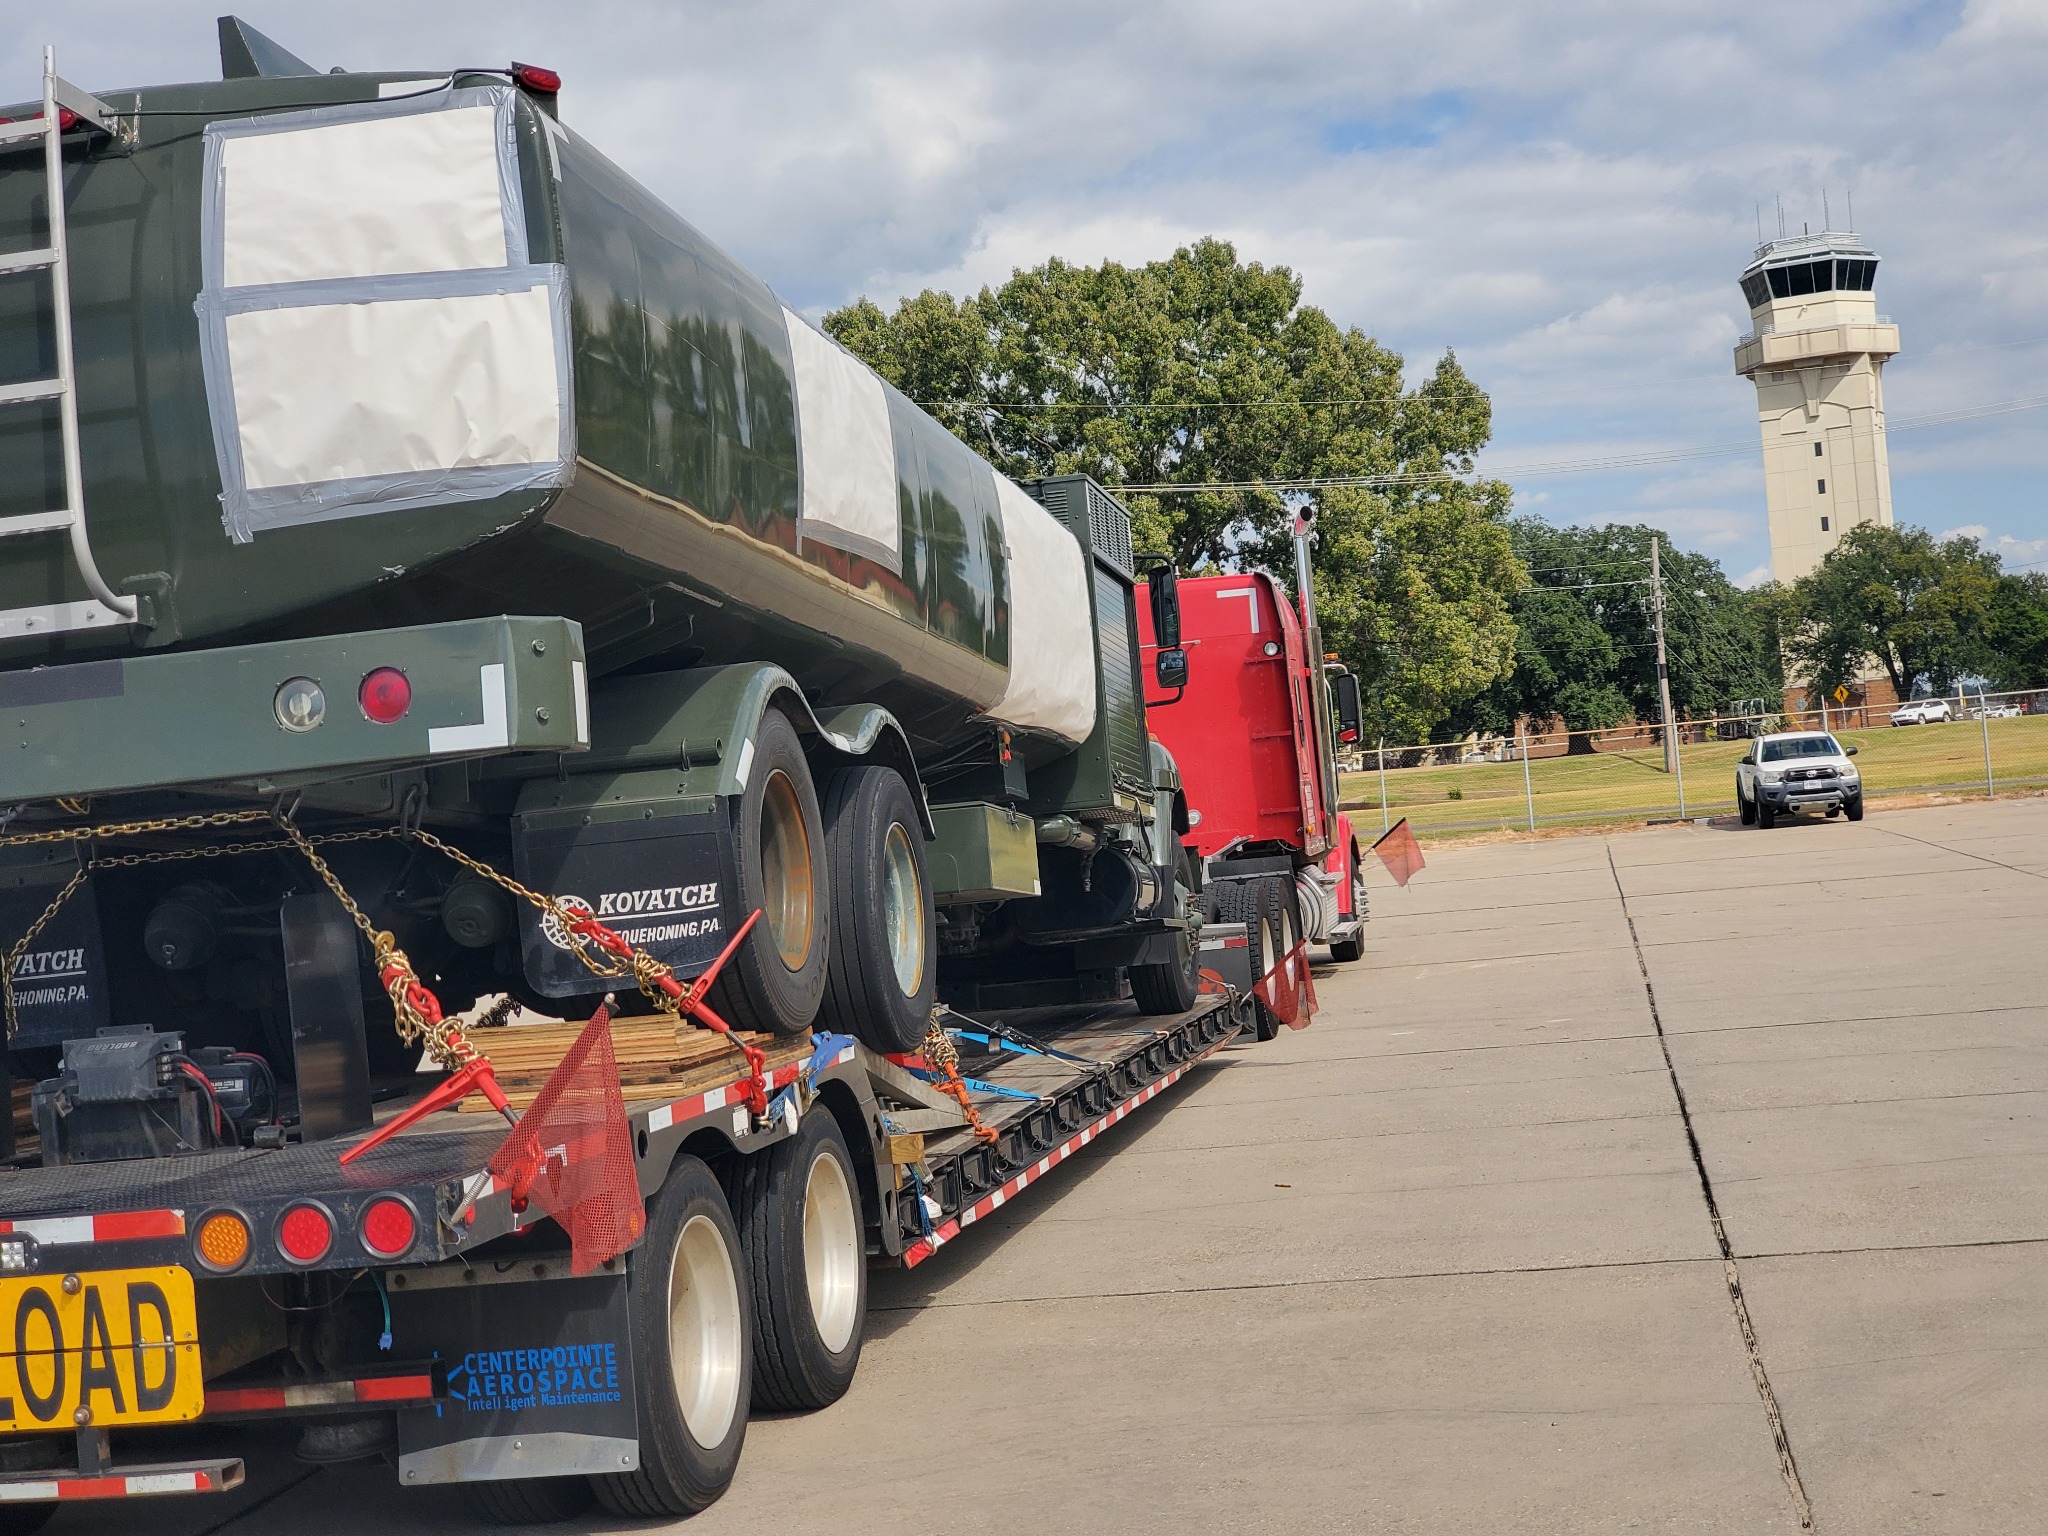
From an owner-operator to an established fleet, the submission should describe the business you actually run.
Commodities, contracts, radius, and operating history.
Temperature-sensitive freight, handling practices, and cargo terms.
Loads, securement practices, equipment, and contractual exposures.
Each operating class is reviewed individually. Market fit and coverage availability are subject to underwriting.
A complete file gives the underwriter a clearer basis for evaluating your operation. It does not guarantee a lower premium or an offer of coverage.
Confirm equipment, drivers, commodities, radius, mileage, revenue, and renewal timing.
Review available loss runs and explain significant events against the supporting records.
Describe corrective actions, verification, results, and unresolved items without changing the original loss reports.
Organize the submission around carrier requirements, market fit, and your coverage priorities.
Loss runs are an essential starting point. They don’t always explain the circumstances or the changes management made afterward.
We document the story behind your loss runs: what happened, what management did, and the outcome. We also maintain a monthly audit trail so underwriters see a well-managed operation at renewal.
Each narrative stays grounded in the records and evidence you provide.
A consistent record helps your underwriting file reflect today’s operation, not just the last policy term.
Collect dated management updates, maintenance records, safety changes, and supporting evidence.
Track the status of corrective actions and note where further documentation is needed.
Organize the history and management response into a clear file for the next underwriting review.
Straight answers to the questions fleet owners ask most.
Auto liability, physical damage, motor truck cargo, general liability, trailer interchange, non-trucking liability, occupational accident, and workers’ compensation where eligible. Availability depends on the operation and underwriting.
As an independent agency, we access multiple carriers and wholesale markets. Which markets fit depends on your operation, radius, commodities, equipment, and loss history.
Yes. See premium financing. Premium financing is available through a licensed third-party premium finance company, which can lower the up-front down payment. Financing is subject to approval and a written premium finance agreement. JJ Reed & Associates may receive compensation from the finance company.
Your USDOT and MC numbers, current declarations pages, five years of available loss runs, an equipment schedule with VINs and values, a driver list, and the commodities and radius you operate.
Ideally 60 to 90 days before your renewal date. That leaves time to gather documents, address underwriting questions, and compare options.
We currently work with trucking operations based in Texas. Coverage can extend to operations that run interstate.
Start a conversation about your coverage, your equipment, or your next renewal.