Homeowners
Structure coverage around your dwelling, belongings, liability, deductibles, and the policy provisions that matter to your home.
A practical review of the policies behind your home, vehicles, recreational vehicles, and personal liability, so you understand your protection and what you retain.
We start with your household, property, and priorities, then compare appropriate coverage options.
Structure coverage around your dwelling, belongings, liability, deductibles, and the policy provisions that matter to your home.
Review liability limits, comprehensive and collision coverage, deductibles, and the people who regularly drive your vehicles.
Dedicated coverage for boats, personal watercraft, and motorcycles, including physical damage and liability. What we review.
Consider additional liability protection above eligible underlying policies, subject to required limits and policy terms.
Match property coverage to rental use, occupancy, property condition, and eligible rental-income exposures.
Evaluate separate flood coverage. Standard homeowners policies generally exclude flood damage.
Explore eligible supplemental coverage that may reduce the amount you retain under a wind or hail deductible. Availability and terms vary. See the deductible strategy.
Many Texas homeowners policies carry a separate deductible for wind and hail claims, set as a percentage of your dwelling coverage. A small percentage can be a meaningful dollar amount.
That percentage is typically calculated using your insured dwelling limit, not the repair cost or the market value of your house.
Use the dwelling value shown on your policy to see the deductible amount in dollars.
This estimate illustrates only a percentage deductible. Depreciation, limits, exclusions, and other policy provisions can affect your total out-of-pocket exposure.
Dwelling coverage × deductible percentage = estimated deductible.
Illustration only. Your policy determines the applicable value and deductible. This is not a coverage determination.
Knowing the valuation method and exclusions helps you choose coverage before weather becomes an issue.
Generally bases covered repairs or replacement on current costs, subject to your deductible, limits, and policy conditions. Roof age or special endorsements may affect how coverage works.
Generally subtracts depreciation for age and condition from the replacement cost. That can leave you with more out-of-pocket exposure beyond the deductible.
May exclude damage that changes appearance without impairing function, such as certain dents or surface marks. The wording and affected materials differ by policy.
Educational context: Texas Department of Insurance: replacement cost and actual cash value. Your policy language controls.
Recreational vehicles need their own coverage. We review how each policy values the vehicle, what it covers away from home, and what the options cost.
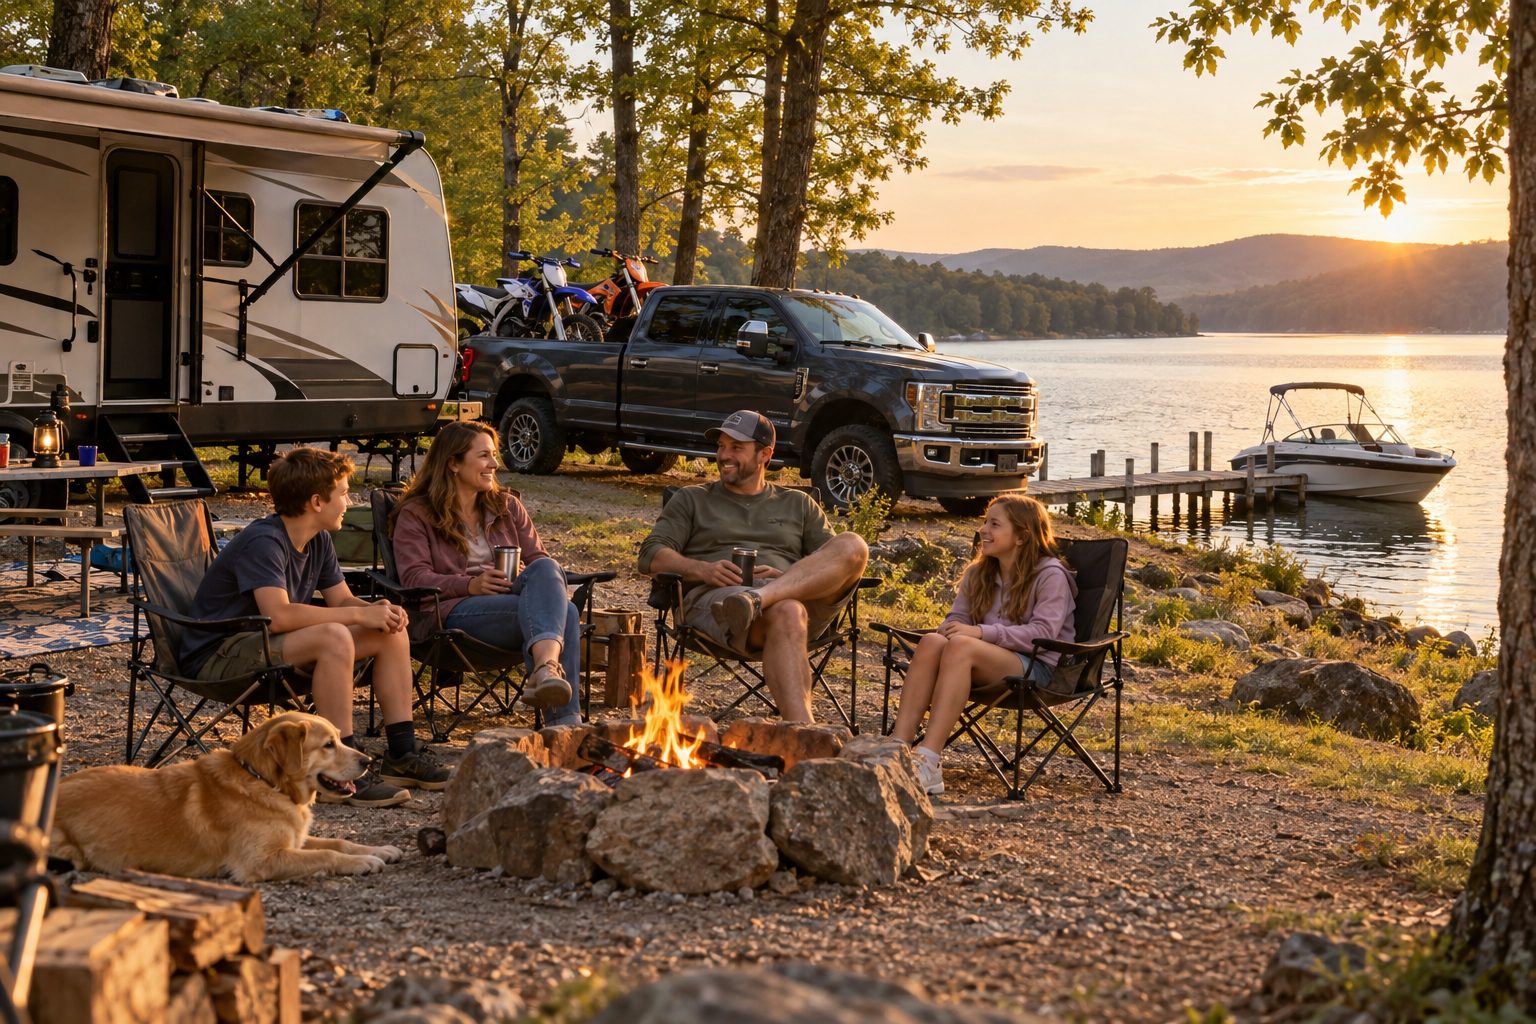
A homeowners policy typically provides only limited coverage for a small boat, often with little or no liability coverage, and generally none for personal watercraft.
Insuring a motorcycle is different from insuring a car. The details that matter most are often the parts you added after you bought it.
Coverage options, limits, and availability vary by carrier and are subject to underwriting and policy terms.
Our complimentary coverage review looks at your deductibles, limits, coverage gaps, and exposures, and explains your options before your next renewal.
Request a coverage reviewStart a conversation about your coverage, your equipment, or your next renewal.